11/10/2026
GELT Bancorp, Inc. Surpasses $2 Billion Asset Milestone Driven by Dedication to Its Local Communities

FOR IMMEDIATE RELEASE
Media Contact:
Lori A. Maley, CPA, President, CEO and Vice Chairman of the Board
(717) 929-2389
GELT Bancorp, Inc. Surpasses $2 Billion Asset Milestone Driven by Dedication to Its Local Communities
Founded in December 2013, Bank of Bird-in-Hand marks third-quarter 2026 earnings with strong community impact and financial momentum.
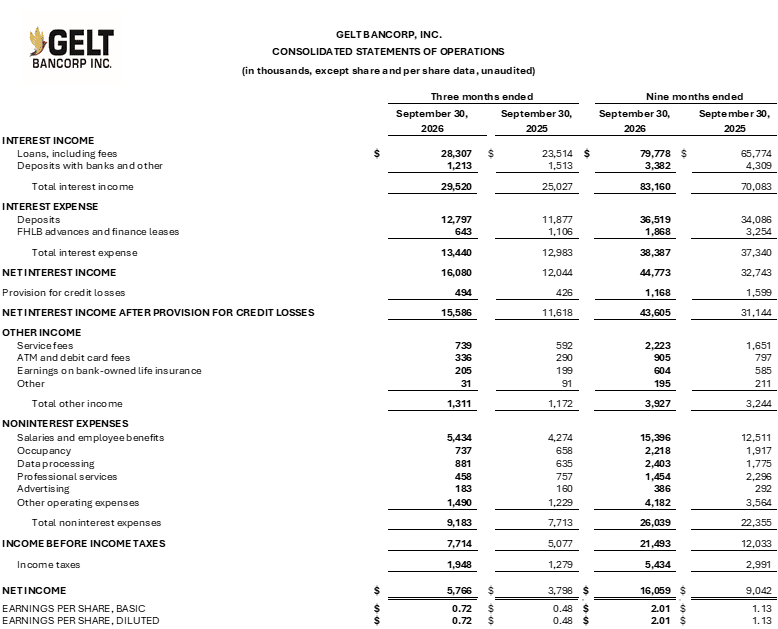
Bird-in-Hand, PA, November 10, 2026 – GELT Bancorp, Inc. (the “Company”), the holding company for Bank of Bird-in-Hand (the “Bank”), announced unaudited operating results for the three and nine months ended September 30, 2026. Third-quarter net income was $5.8 million, or $0.72 per share, compared to $3.8 million, or $0.48 per share, a year earlier. For the first nine months of 2026, net income was $16.1 million, or $2.01 per share, compared to $9.0 million, or $1.13 per share, in the same period of 2025.
Lori A. Maley, CPA, President, Chief Executive Officer and Vice Chairman of the Board stated, “Crossing the $2 billion asset milestone this quarter is a powerful validation of our founding mission from December 2013: to be a true partner to the people and businesses in the communities we call home. Thirteen years later, we achieved this milestone by sticking to our core mission and making good on our promises to the local communities we serve. Our growth is a direct reflection of the trust our customers place in us. Additionally, our growth is a testament to the strategic leadership of our board of directors, our enduring corporate culture, and the incredible staff of committed, dedicated individuals who make this Bank great every day. As we look ahead, we remain entirely focused on ensuring our financial success translates directly into continued prosperity of our neighbors and local markets.”
Highlights for the third quarter of 2026:
Financial Performance:
- Surpassed the $2 billion in total assets, milestone
- Third-quarter net income increased 51.8% from the prior-year quarter
- Loans and deposits grew 13.6% and 12.4%, respectively, from year-end 2025
Community & Franchise Impact:
- Welcomed over 3,800 customers, shareholders, and neighbors at the Bank’s annual picnic
- Donated approximately $260,000 to area non-profit organizations year to date, supporting regional economic development and community services
Results of Operations
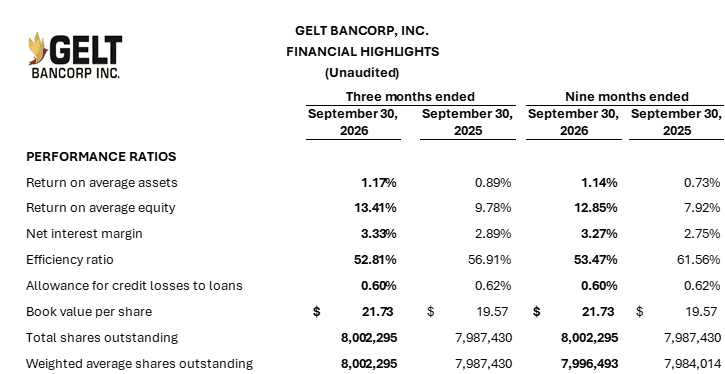
“Our strong performance this quarter demonstrates that our disciplined approach to scaling the balance sheet is translating into strong operational results,” stated Ms. Maley. “Crossing the $2 billion asset threshold has unlocked meaningful operating leverage, allowing us to expand our year-to-date net interest margin to 3.27% and drive year-to-date net income to $16.1 million. This strong profitability is a direct result of our team’s execution, steady core deposit growth, and a robust loan pipeline across the communities we serve. These results demonstrate our ability to drive sustained, profitable growth and create long-term value for our shareholders.”
Third-quarter net interest income increased to $16.1 million from $12.0 million a year earlier. Net interest margin expanded to 3.33% from 2.89%, supported by higher loan yields and lower funding costs. The provision for credit losses reflected organic loan growth and the Bank’s strong and stable asset quality.
Other income increased, primarily reflecting higher service charge income associated with increased loan volume. Noninterest expense increased as the Bank invested in staffing, data processing, and other operating needs. Despite these higher costs, the third-quarter efficiency ratio improved to 52.8% from 56.9% a year earlier.
Financial Condition and Capital Management
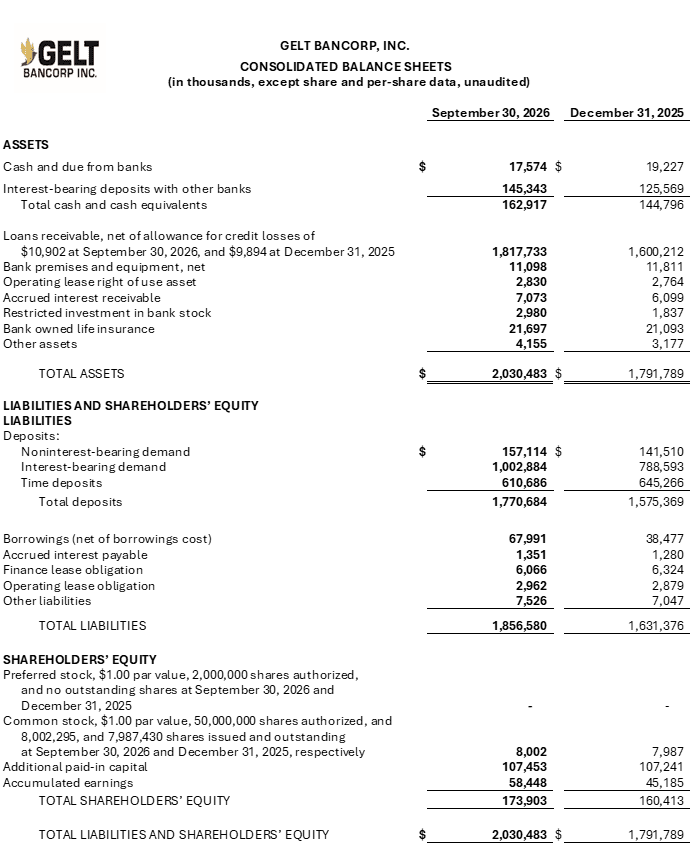
Total assets reached $2.03 billion at September 30, 2026, reflecting steady organic growth across the Bank’s multi-county footprint. Loan growth was particularly strong in the commercial and industrial, and agricultural portfolios. Cash and cash equivalents also increased, supporting on-balance sheet liquidity.
Total deposits reached $1.77 billion at September 30, 2026. Growth reflected new customer relationships and retention of existing balances amid heightened pricing competition. The deposit mix shifted away from higher-cost certificates of deposit toward demand deposits.
Stockholders’ equity increased to $173.9 million at September 30, 2026, as earnings more than offset the common stock dividend paid in April. Book value per share reached $21.73.
Bank of Bird-in-Hand maintained regulatory capital levels above statutory well-capitalized thresholds at September 30, 2026, supporting ongoing organic loan demand and the financial needs of its communities.
Asset Quality
Asset quality remained strong, with nonperforming loans representing 0.20% of total loans at September 30, 2026, compared to 0.19% at year-end 2025. Management believes the Bank’s overall credit quality metrics remain sound and within historical ranges.
About Bank of Bird-in-Hand and GELT Bancorp, Inc.
GELT Bancorp, Inc. is the registered bank holding company of Bank of Bird-in-Hand, a Pennsylvania-chartered bank subsidiary, with a strong focus on agricultural, small business, and consumer lending. Its main branch and office is located at 309 North Ronks Road, Bird-in-Hand, PA 17505. It operates additional brick-and-mortar branches and mobile bank branches called the GELT or Money Buses in Lancaster, Lebanon, Dauphin, Chester, Berks, and Schuylkill counties. For additional information, including a list of all branches, please visit our website at https://bihbank.com/. Member FDIC.
If you are interested in learning more about the company’s investment story and would like information regarding stock ownership, please visit our website at https://bihbank.com/investor-relations/ or contact Investor Relations at [email protected], 717-929-2389.
A Warning About Forward-Looking Statements
This press release contains statements about our plans, objectives, expectations, and intentions as well as other statements that are not historical facts. These are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities and Exchange Act of 1934. These forward-looking statements can be identified by use of terminology such as “expect”, “plan”, “anticipate”, “believe”, “estimate”, and similar words that are intended to identify such forward-looking statements. These forward-looking statements are based on management’s current expectations, assumptions, estimates, and projections about the Bank and the Company, the financial services industry, and the economy. There are several factors such as changes in fiscal or monetary policy, or changes in the economic climate that will influence the future operations of the Bank and the Company. These factors are difficult to predict with regard to how likely and to what degree or significance that they would occur and are subject to change. Actual results may differ materially from what may have been forecast in the forward-looking statements. Readers are accordingly cautioned not to place undue reliance on forward-looking statements. The Bank and the Company do not revise or update these forward-looking statements to reflect events or changed circumstances.
Related Blogs
10/05/2026
A Bank Customer Fraud Story: How Our Honey Brook Team Stopped a $20,000 Scam
08/20/2026
Safeguarding Your Identity: A Guide to Preventing Synthetic Identity Fraud
07/09/2026
Annual Bank of Bird-in-Hand Community Picnic